What a Federal Spending Proposal Actually Promises
A federal spending proposal is a proposed congressional action that creates, changes, or funds federal expenditures. The legislative text establishes what the government would commit to doing. An announcement describes a proposal; enacted funding establishes legal authority; payment records show money actually disbursed. Those stages deserve separate entries whenever voters assess a federal promise.
An accounting lens supplies a useful sequence: identify the commitment, trace the money, test assumptions, and check results. It brings fiscal accountability to claims heard on the campaign trail without deciding which public purposes deserve priority.
The practical deliverable is a repeatable comparison sheet connecting federal budget claims to Texas implementation. Start with the proposal identifier, chamber, version date, legislative status, administering agency, and claimed Texas benefit. Keep proposed funding, enacted funding, obligations, and outlays in separate fields.
Federal finance differs from household budgeting. This framework organizes fiscal claims; questions about distributional fairness, economic trade-offs, and Texas priorities still require policy judgment.
Trace the Route From Congress to a Texas Community
First identify the delivery route. A payment to an eligible individual, a grant administered by a state or local recipient, and a federal contract create different responsibilities. Direct benefits and federal procurement can reach Texas residents without passing through the state treasury.
- Authorization establishes or changes a program.
- Appropriation provides budget authority.
- Obligation records a legally binding commitment.
- Outlay records a payment.
Authorization and appropriation can occur through different legislative mechanisms. Inspect the actual provisions rather than assuming that passage of any spending-related bill supplies every authority needed for payment.
Formula funding follows statutory allocation factors. Check eligible recipients, any required state plan, and how local projects receive selection. Competitive grants require attention to application deadlines, selection criteria, required attachments, matching contributions, and the entity responsible for applying.
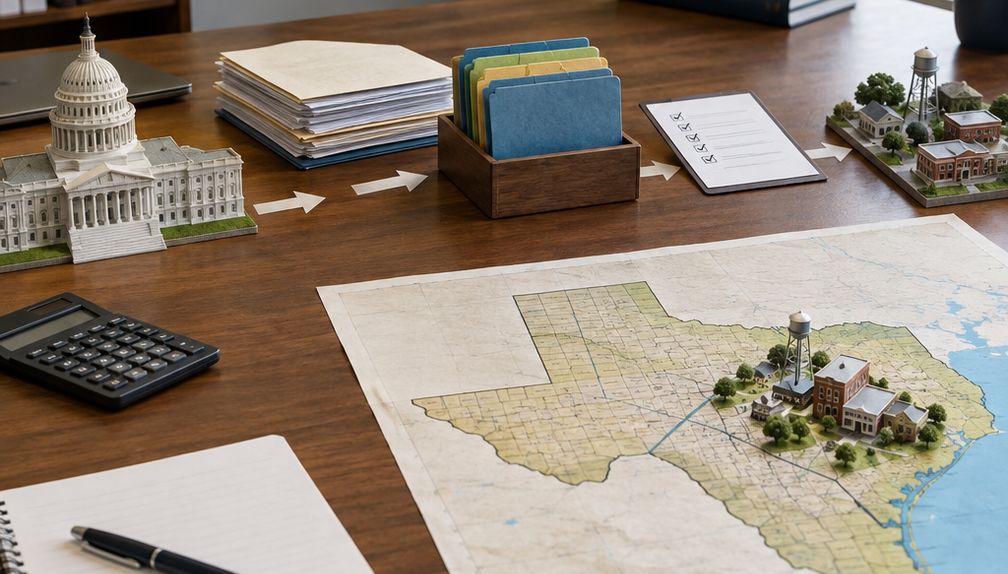
For a grant-funded project, distinguish the federal agency’s obligation to a recipient, the recipient’s payment request, and the utility’s payment to its contractor. Advances and reimbursements produce different cash-flow sequences. The eligibility provision, assistance agreement, and payment conditions establish which sequence applies.
Read the Price Tag Beyond the Headline
A useful cost estimate belongs to a specific proposal version. If the text changes, an earlier estimate remains evidence about the earlier text until its applicability is established.
Cost Estimate Checks
- Match the proposal version and estimate publication date.
- Record the budget window’s start and end and the baseline used for comparison.
- Read the annual spending pattern, including delayed payments.
- Identify whether the headline measures budget authority or expected outlays.
- Check administrative expenses and commitments extending beyond the displayed window.
Mandatory spending operates through substantive law; discretionary funding comes through appropriations. Tax provisions change revenue. Benefits marketed in similar language can therefore reach the budget through different mechanisms.
Keep gross program spending separate from net budget effects after offsets. Record spending increases, spending reductions, revenue changes, and the resulting deficit effect separately. Implementation delays may shift payments between years while leaving continuing responsibilities intact.
Any eventual budget figure should carry its source document and publication date. Use the relevant congressional cost estimate or tax estimate, with the applicable table or provision, rather than an unattributed campaign summary.
Check Who Pays and What Texas Must Commit
Financing can combine additional revenue, reductions elsewhere, and borrowing. Each choice raises a distributional question: which taxpayers, program recipients, or places bear the change? A national net figure cannot answer that question for north Texas communities.
For each proposed offset, identify the legal change, when receipts or savings begin, whether they recur, and whether those resources already support another commitment. Compare the offset’s duration with the spending obligation. A temporary receipt leaves recurring expenses to be financed later.
Unpriced Local Commitments
An unspecified local contribution remains an unanswered affordability question. Preserve that uncertainty on the worksheet rather than entering zero or treating the omission as grounds for automatic rejection.
Local costs begin before construction. Application preparation, procurement administration, construction oversight, and staffing can require resources. Matching requirements need an eligible cost base, permitted cash or in-kind contributions, payment timing, and a legally responsible entity.
Then examine cash flow. If the recipient must pay invoices before reimbursement, identify the source of interim cash. Separate construction assistance from the utility’s continuing operation, preventive maintenance, and eventual replacement responsibilities.
Look for a Named Owner, Public Records, and Measurable Results
Accountability begins with a named administering agency, recipient, and delivery owner. The governing statute and award terms establish which eligibility controls, award conditions, expenditure reports, procurement requirements, audits, corrective actions, and recovery provisions apply. Their applicability varies by program.
Compliance and effectiveness require separate judgments. A supported payment establishes a documented transaction. Useful service requires evidence about delivery and results. An audit finding also needs interpretation; it does not automatically establish fraud.
Match Records To Claims
An award announcement supports an award claim. Payment records support a payment claim. Construction acceptance documents and operating reports address completion and service.
For water infrastructure, track money awarded, payments made, construction accepted, and service delivered as distinct milestones. Reconcile federal award records with recipient financial reports, contractor payments, and acceptance documents where available.
Choose measures that fit the objective: completion against the approved schedule, cost per completed connection, service interruptions, or access for intended recipients. Each measure needs a reporting period, denominator, responsible entity, and public reporting location. A reliability claim should identify the customers or connections covered and the observation period.
Put Competing Economic Platforms on the Same Worksheet
Consistent definitions make comparison possible. Align budget windows, baselines, revenue treatment, and the distinction between spending authority and payments before comparing headline costs or benefits. Unequal time periods should remain visible; dividing totals into equal annual amounts can conceal the actual spending pattern.
| Comparison field | Proposal A | Proposal B | Evidence still needed |
|---|---|---|---|
| Policy objective | Unspecified | Unspecified | Purpose in legislative text |
| Delivery mechanism | Unspecified | Unspecified | Payment, grant, or contract provisions |
| Eligible Texas recipients | Unspecified | Unspecified | Eligibility and allocation rules |
| Cost window | Unspecified | Unspecified | Dated estimate, baseline, annual tables |
| Financing | Unspecified | Unspecified | Revenue, reductions, borrowing, offset timing |
| Local obligations | Unspecified | Unspecified | Match, staffing, maintenance, cash flow |
| Implementation schedule | Unspecified | Unspecified | Application, award, and delivery milestones |
| Outcome reporting | Unspecified | Unspecified | Measures, reporting owner, public location |
As evidence arrives, label entries documented, assumption-dependent, or unspecified. Retain the source title, date, and relevant page or provision. Name assumptions explicitly, such as participation, construction prices, implementation timing, or projected growth.
Bring Three Water-Funding Questions to a Congressional Town Hall
Consider an explicitly hypothetical proposal to replace aging drinking-water pipes in a Texas community. Its objective is understandable. Local affordability and delivery timing remain unverified until the proposal establishes eligibility, financing terms, and implementation responsibilities.
Construction assistance may address pipe replacement while leaving the utility responsible for future inspection, leak repair, staffing, and replacement. The proposed terms should identify who pays each expense.
- What provision makes this community eligible?
- What funding and ongoing costs must the local utility cover?
- Where will residents see payments, construction milestones, and service results?
In an illustrative Plano town-hall scene, a resident unfolds the worksheet on a chair. The row for local obligations still reads “unspecified.” When questions begin, the resident points to that row and asks who would cover maintenance after construction funding ends. A pen rests beside the empty source field, ready to record the provision cited in the answer.